




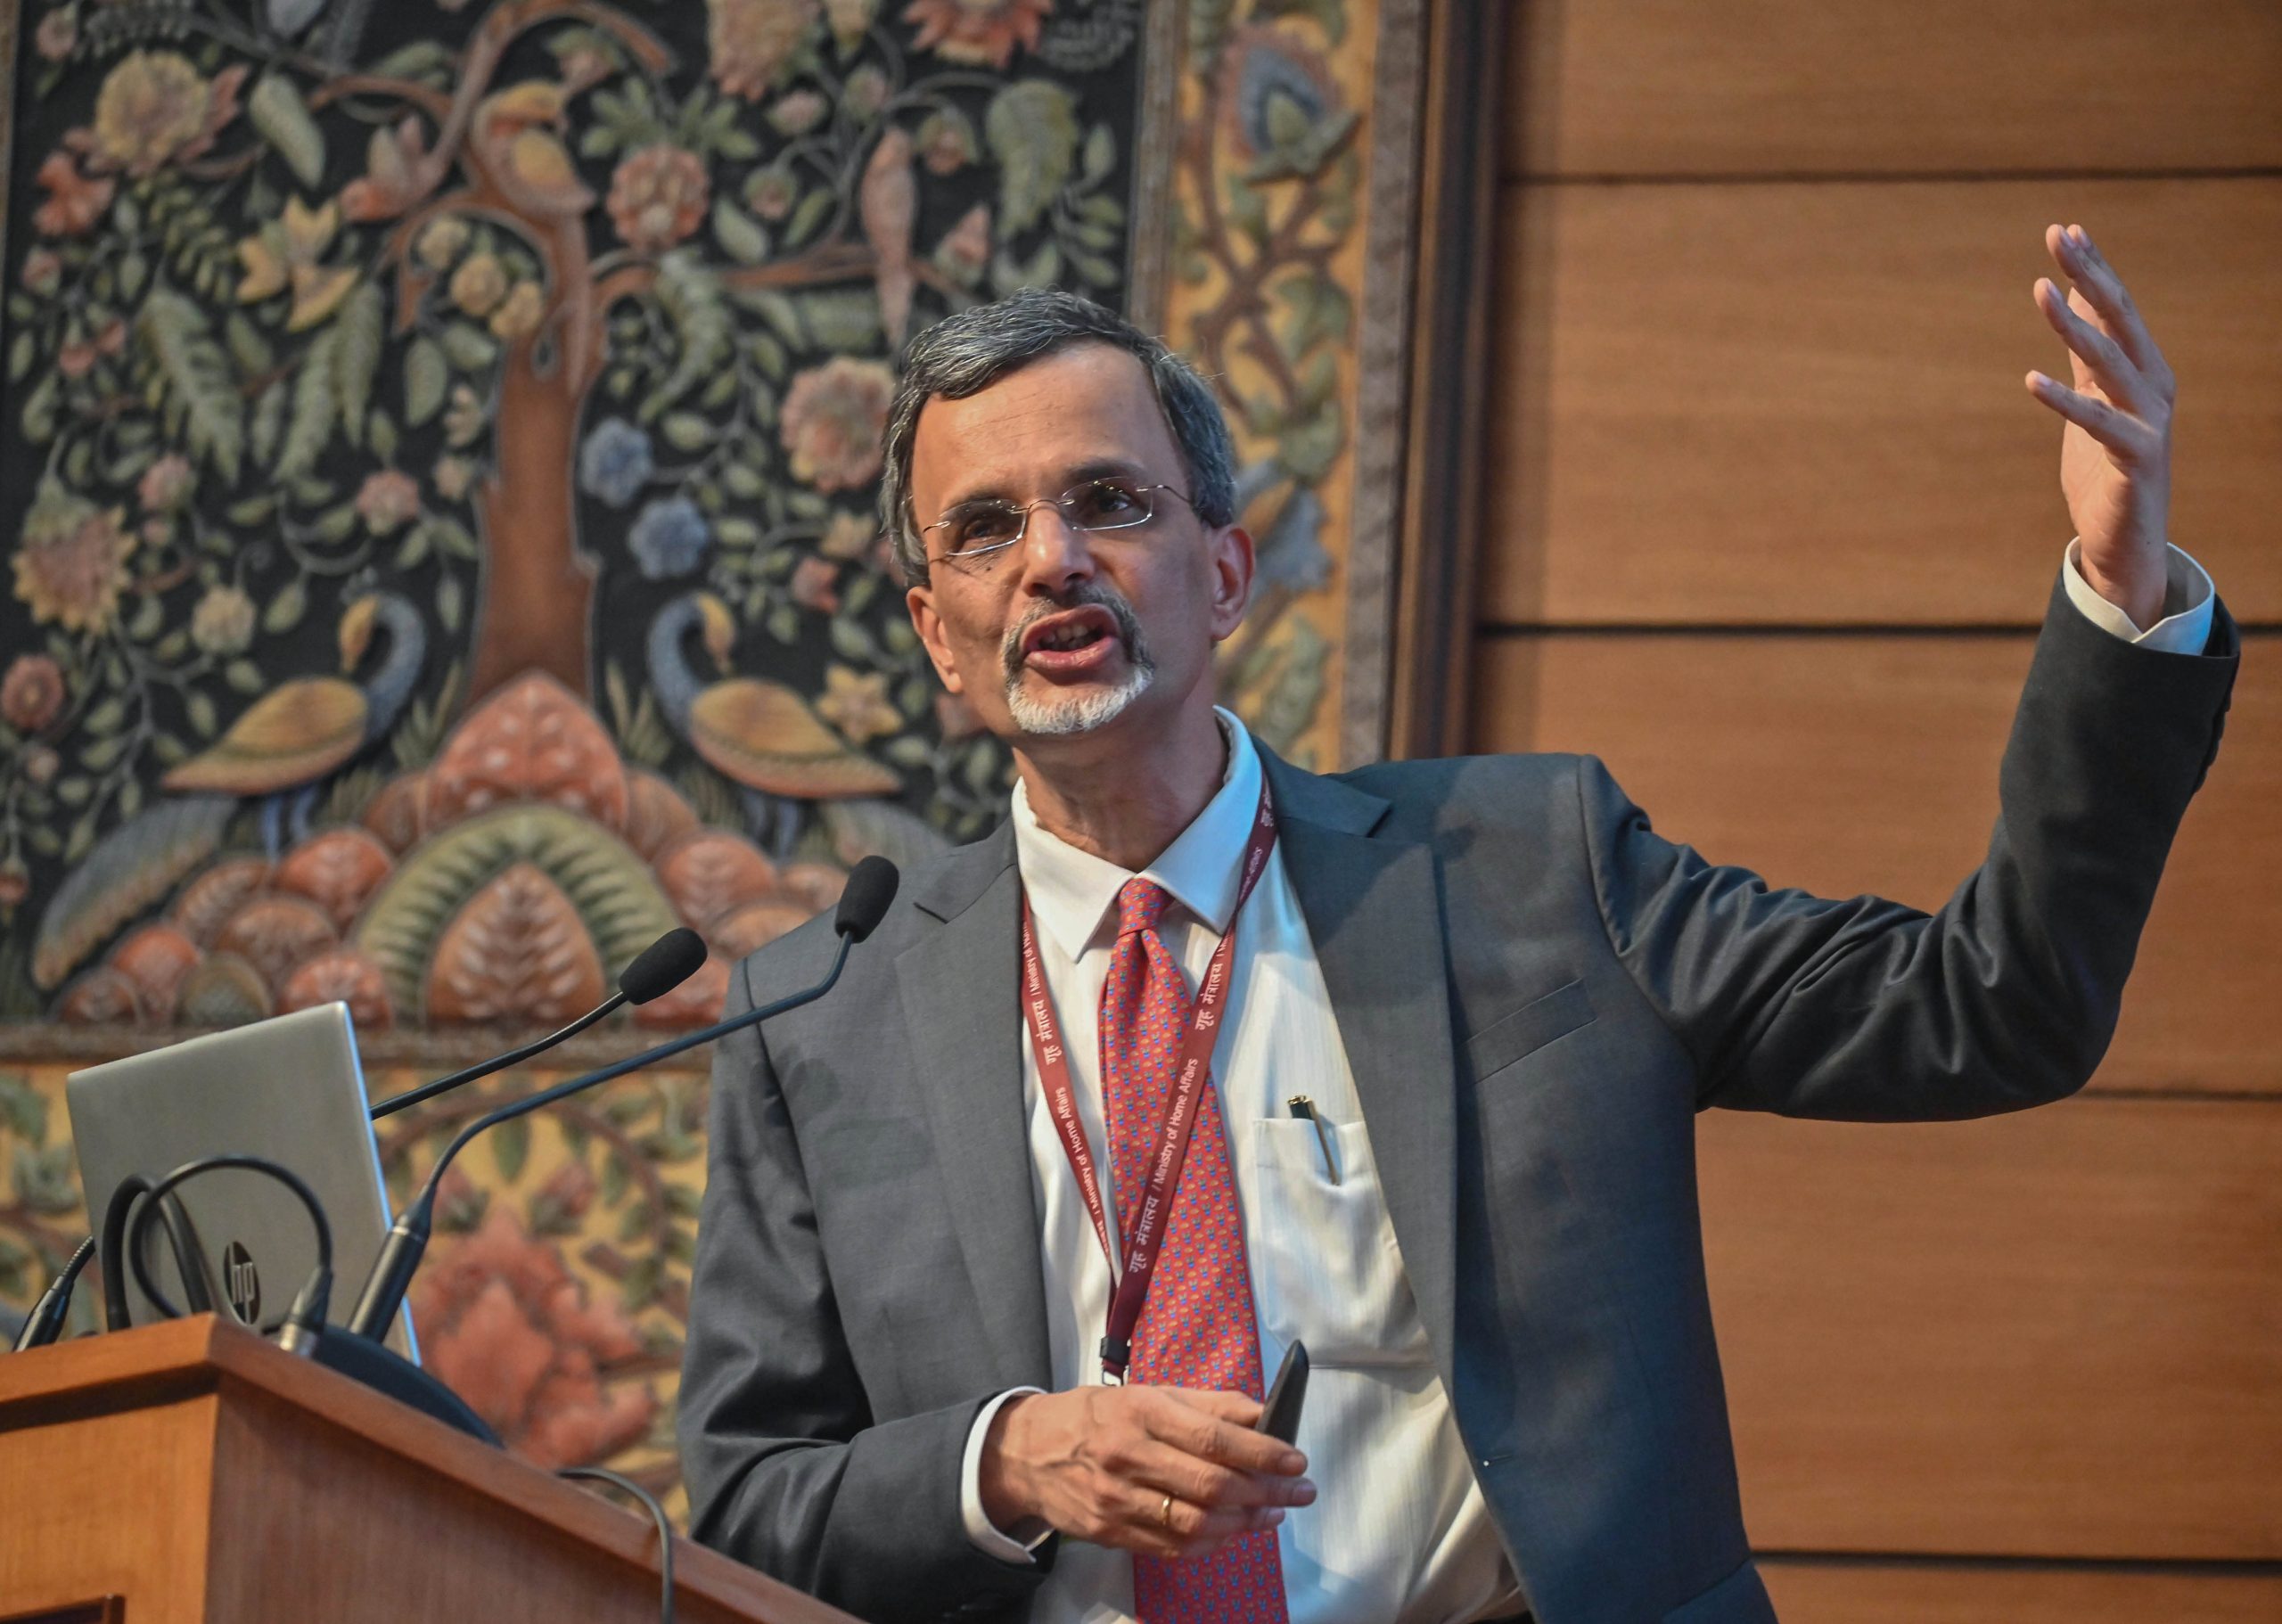
India needs to encourage households to commit a larger share of their savings to long-term pension products as pension and insurance assets continue to account for a relatively small share of household savings, Chief Economic Adviser V Anantha Nageswaran said.
Speaking virtually at an event marking NPS Diwas 2025-26, Nageswaran said Indian households have changed their saving patterns, with a significant increase in market-linked investments, but pension savings have not risen at the same pace.
“The Indian saver has shown a willingness to accept market risk or so we would like to believe. What the saver has not yet done at scale is to commit savings for a longer tenure,” he said.
Nageswaran said encouraging long-term savings would require greater trust in financial institutions, accessible financial information and simpler products that do not require savers to become financial experts.
Citing data from the Economic Survey, he said the share of equity and mutual funds in annual household savings increased from around 2 per cent in 2011-12 to about 15 per cent in 2024-25. During the same period, the share of bank deposits declined from more than 58 per cent to around 35 per cent.
Monthly systematic investment plan (SIP) flows also increased from less than Rs 4,000 crore in 2016-17 to more than Rs 28,000 crore during the first eight months of 2025-26.
However, the share of pension and insurance assets in household savings remained unchanged between 2018-19 and 2023-24, highlighting the need for wider pension coverage.
Nageswaran said India’s total pension assets stood at around 17 per cent of GDP, compared with at least 80 per cent in OECD peer countries, indicating considerable scope for expansion.
He said technology and simpler pension products could help bridge the coverage gap, drawing a parallel with the experience of the Unified Payments Interface (UPI).
“The experience of UPI is quite illuminating,” he said, adding that financial inclusion could precede financial literacy.
He said the National Pension System had also adopted measures in this direction, including default schemes, small contributions that can be made through a mobile phone and the involvement of locally known agents.
Initiatives such as Tatkal NPS and Pension Sakhis, he said, were also aimed at improving pension coverage.
Nageswaran stressed that building a pension corpus was only one part of ensuring retirement security. The system must also provide a reliable stream of income after retirement.
“A corpus at 60 years of age is only half the job. The other half is converting it into a steady income that lasts for as long as the person lives and one that keeps pace with prices or inflation,” he said.
He added that retirement-income schemes, drawdown mechanisms and assured payouts would need continued attention in the coming years to strengthen India’s pension system and provide greater retirement-income security.
-ANI


